The fine print, side by side
Rates get the headlines, but the features in a mortgage decide what it costs when your plans change. This report compares those features at 11 Canadian lenders in one place, so you know what to ask before you sign.
$29 Canadian dollars, plus sales tax where it applies. One-time purchase.
Buy the report, $29A 21-page PDF, Fall 2026 edition, terms checked November 2, 2026. The download link is emailed to you as soon as you pay.
What's inside
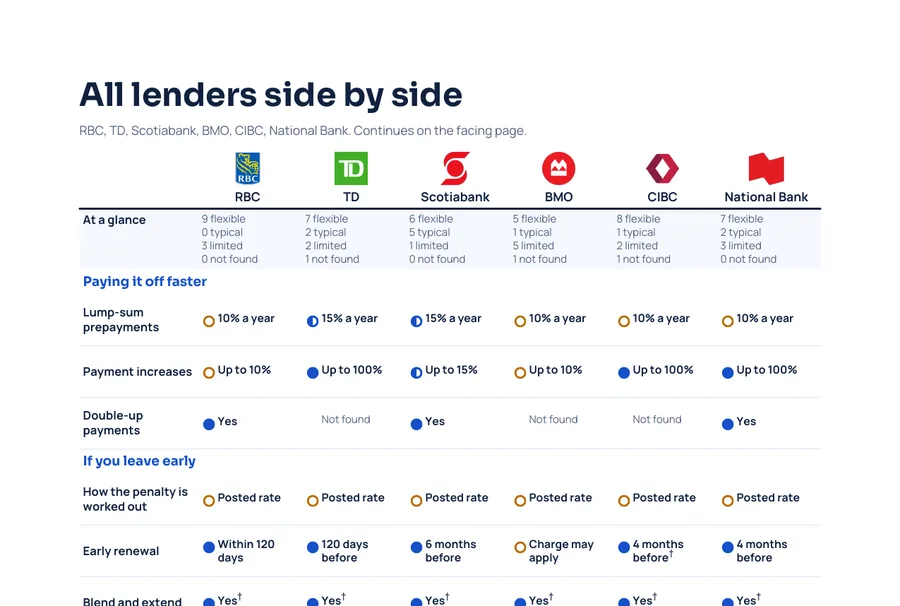
- All 11 lenders side by side on two facing pages, with the same 13 features in every row: lump sums, payment increases, double-up payments, how the fixed-rate penalty is worked out, early renewal, blend and extend, portability, a buyer taking over the mortgage, standard or collateral charge, variable payments, locking in, rate holds and skipping a payment.
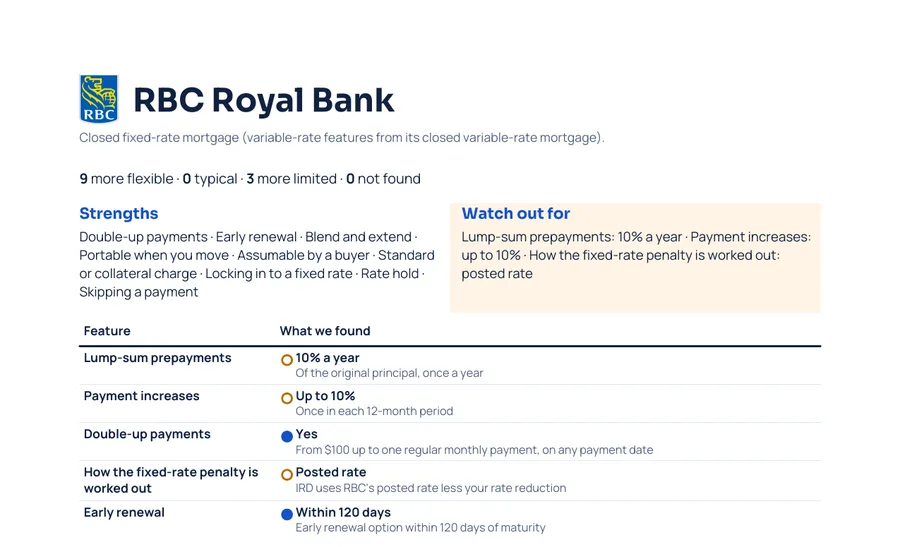
- One page per lender, each on the same grid, with its strengths, what to watch out for and what to ask.
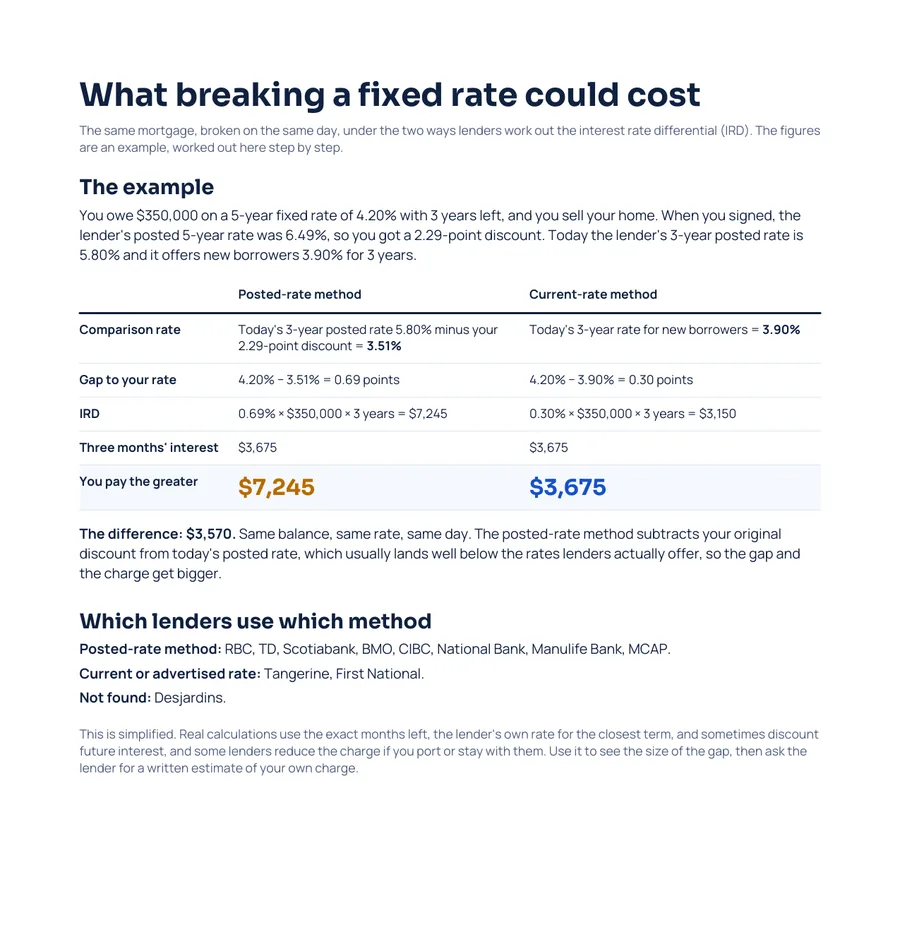
- What breaking a fixed rate could cost: the same mortgage worked out under both penalty methods, and which lenders use which.
- Who stands out for what: the most flexible lenders for paying it off faster, leaving early, moving, variable rates and extras.
- What each feature means for you, with an example and the questions to ask.
- A question checklist to take to your meeting, and a glossary of every term and short form.
Lenders covered: RBC Royal Bank, TD Canada Trust, Scotiabank, BMO, CIBC, National Bank, Desjardins, Tangerine, Manulife Bank, First National and MCAP.
A look inside
How the report is made
Where it comes from. All information is referenced from lender websites and other online sources: each lender's product pages, mortgage terms and published documents first. Where a lender doesn't publish a feature, other online sources fill the gap, and those values are marked with a dagger (†) so you know to confirm them. Every lender page lists its sources.
Nothing is guessed. When a feature can't be found, the report says "Not found" and adds it to that lender's list of questions to ask.
How the marks work. Each feature has a fixed rule, the same for every lender, for marking it more flexible, typical or more limited. Marks compare a lender with that rule, not with the other lenders.
Independent. No lender pays for, reviews or approves the report. Lender logos are used with each lender's permission.
Kept current. The lenders' terms are checked regularly, and a new edition comes out when something changes. Each edition lists what changed since the last one.
Questions
What format is it? A PDF that opens on any phone, tablet or computer, with bookmarks for every section and lender. It prints well too.
How do I get it? Right after you pay, you get an email with a download link. Your copy carries your email address.
Is it advice? No. It describes the terms lenders advertise. Your own mortgage agreement has the final word, so confirm every feature with the lender before you sign.
Do I need it if the rates on this site are free? The rates stay free. The report covers what the rate tables can't: the terms that decide what a mortgage costs when your plans change.